5 Real Reasons for Being Denied a Bank Account in Hong Kong: Unclear Business Model, Conflicting Information, Social Security Records That Don’t Match Business Activities… The Third One Is the Most Common
Published: July 22, 2026
You worked so hard to prepare all the documents, only to be turned away by the bank with a simple “Your comprehensive assessment did not pass”—that feeling is even more painful than not having prepared at all. What’s even worse is that you don’t even know where you went wrong.
We’ve reviewed cases of account opening rejections we’ve encountered over the past few years and identified the five most common reasons. If you’re preparing to open an account or have just been rejected, we hope this analysis will help guide you.
💡 Was your account application rejected and you don't know why? Add WeChat ID qcygscszk or call 18676749275, and send 【Rejection Diagnosis】 to receive a free analysis of the reason and a solution.
Reason for Rejection #1: Unclear Business Model (Frequency: High)
This is the most common—and most easily overlooked—issue. When asked, “What does your company do?”, many clients give answers that are either too broad—“We’re in trade”—or too vague—“We do a little bit of everything.” From a bank manager’s perspective, such responses suggest that your business direction is unclear and that your operational risks are relatively high.
The right approach is this: within one minute, you should be able to clearly explain what your product is, where your customers are, how your supply chain works, and how your cash flows. This isn’t about “preparing for an interview”; it’s about demonstrating your command of your own business. For a business owner who is truly running their business, this information should come naturally.
Common Mistakes vs. Correct Examples: ✘ “We’re in the cross-border e-commerce business, and we sell a lot of things.” ✔ “We specialize in outdoor sports gear, which we sell through Amazon’s North American and European marketplaces. Our suppliers are primarily based in Zhejiang and Fujian, and our monthly sales are approximately $50,000. We’re currently planning to expand into the Southeast Asian market—which is why we need to open a Hong Kong account.”
Reason 2 for Rejection: Conflicts between documents (Frequency: High)
A bank’s review isn’t just about whether you have the necessary documents; it’s about whether those documents “corroborate” one another. If the sales contract you provide to the bank shows that you’re in the electronics business, but your bank statements are full of payments from the food and beverage industry—once the bank discovers this discrepancy, your credibility will instantly plummet to zero.
Another common discrepancy is when the contract amount doesn’t match the bank statements. You claim to have a monthly turnover of 1 million HKD, but the bank statements you provide show only a few tens of thousands in monthly transactions. The bank manager won’t call you out on it in person, but he’ll note in his internal review report that “the information provided by the client does not match their statement.”
Reason 3 for Rejection: Social Security History and Experience Do Not Align with the Company’s Business (Frequency: Highest)
This is the most common reason for an “instant rejection,” and it’s the one that traps the most people. The bank’s reasoning is simple: your company is in the cross-border e-commerce business, but your social security records consistently show that you’ve been working at a traditional manufacturing plant. The bank has reason to suspect that you might be acting as a “nominee” for someone else’s account, or that your company doesn’t actually have an operator at all.
A special note here: Not all banks are strict enough to require a perfect match in industry, but “broadly related” is the basic minimum requirement. For example, if you previously worked as a foreign trade order processor and have now started your own cross-border e-commerce business—this connection in experience is acceptable to banks. However, if you switch directly from the restaurant industry to cross-border e-commerce without any transitional experience or professional background in the field, banks will consider the risk to be relatively high.
Reason 4 for Rejection: Involves sensitive countries or industries (Frequency: Moderate)
Every bank has its own “negative list”—transactions involving certain sanctioned countries or high-risk industries (such as cryptocurrency, precious metals trading, and gambling-related activities) will result in the bank directly rejecting account opening applications. Many customers only realize after being rejected that their client list happens to include regions where the bank does not permit transactions.
The best way to handle this issue is to “check in advance.” Before selecting a bank, find out which countries and industries the bank has restrictions on. There are significant differences between banks—for example, Overseas-Chinese Banking Corporation (OCBC) is significantly more open to countries along the “Belt and Road” route than HSBC.
Reason 5 for Rejection: The account’s stated purpose does not match its actual use (Frequency: Moderate)
The bank can monitor whether the “account purpose” you provided when opening the account matches how you actually use it. If you stated that the account was for “receiving payments from cross-border e-commerce” when opening it, but your first transaction after opening the account is a large personal transfer, the bank’s risk control system will most likely flag your account as suspicious.
What should you do if you're rejected?
First, don’t immediately switch to another bank and “try your luck.” Banks share risk information with one another, and a record of being rejected by two banks in a row will seriously affect your chances of successfully opening an account in the future. The correct approach is to first determine the reason for the rejection, provide the necessary supplementary documents to address the specific issue, and then choose a bank that’s a “good fit” to resubmit your application.
Second, take a fresh look at your business structure. Sometimes a rejection isn’t due to “bad luck,” but because your business isn’t quite ready yet. In such cases, the most efficient approach is to take a step back, refine your business fundamentals, and then initiate the account opening process.
📞 If you’ve been rejected once or multiple times and aren’t sure how to resolve the issue, feel free to contact Qicaiying for a personalized solution. Just send a message with the text 【Account Opening Remedies】 to WeChat ID qcygscszk.
Why choose Enterprise Caiying
What Can We Do for You—
✔️ Hong Kong Company Registration: Full-service agency, registered office address, and a valid business address for bank KYC verification—not a virtual address
✔️ Fast-Track Bank Account Opening: We have established "whitelist" partnerships with banks such as HSBC, Overseas-Chinese Banking Corporation, Hang Seng, and Dah Sing, and pre-screen documents to increase the success rate of account openings.
✔️ One-stop, end-to-end support: From company registration to opening a bank account, annual reviews, bookkeeping, and audits—a dedicated representative will handle everything for you, so you don’t have to go through the process yourself.
✔️ Cross-border Tax Planning: Hong Kong Certificate of Residence (CoR) and CRS compliance strategies to help you prevent unnecessary exchange of tax information
✔️ Local on-the-ground team in Hong Kong: 3 licensed secretarial firms + 1 in-house Hong Kong accounting firm; government correspondence and bank verifications are handled locally; bookkeeping and auditing are not outsourced
Why You Can Trust Us—
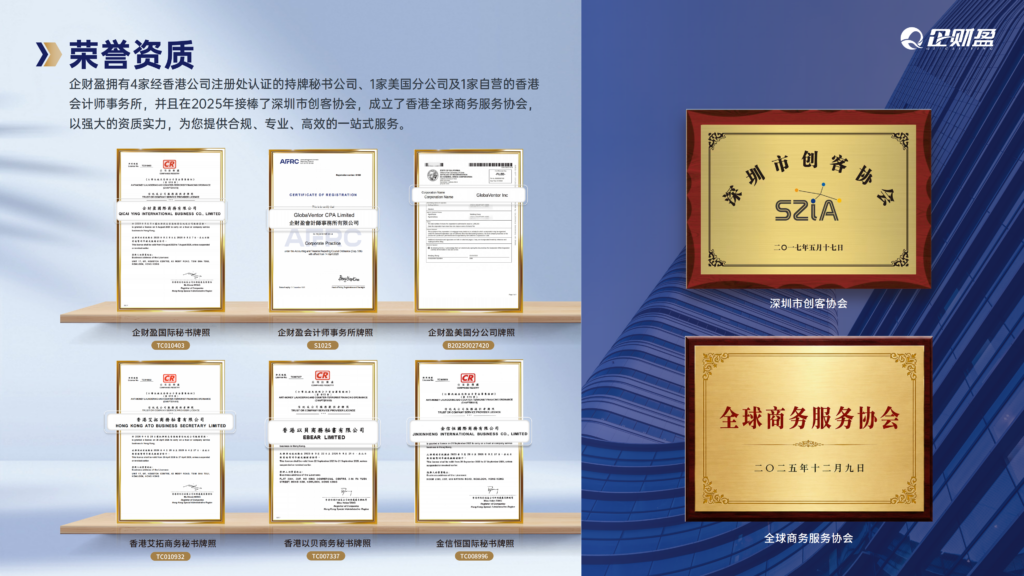
✔️ Hong Kong Licensing Qualifications: Three licensed secretarial firms certified by the Hong Kong Companies Registry—not ordinary agencies—that possess the qualifications of a statutory secretary
✔️ In-house accounting firms: 1 self-operated Hong Kong accounting firm + a Greater Bay Area accounting firm; audit reports are not outsourced
✔️ Endorsed by industry associations: Vice President of the Shenzhen Bookkeeping Services Association; Board Member of the Shenzhen Cross-Border E-Commerce Association
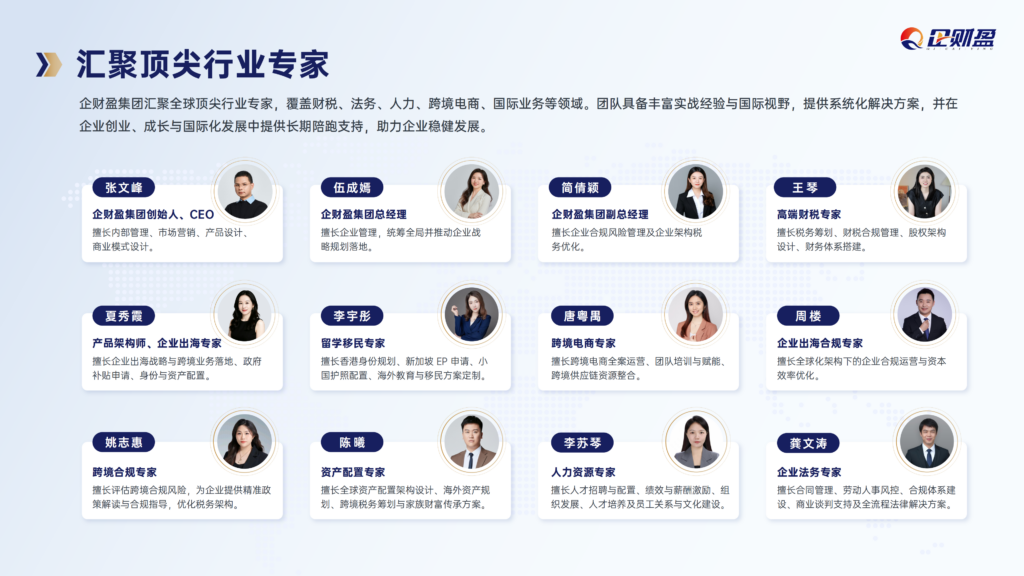
✔️ Founded in 2015, we have served over 500,000 small, medium, and micro enterprises with a team of over 400 professionals, including lawyers, CPAs, tax consultants, and cross-border compliance experts. Our core team members have an average of 8–15 years of industry experience.
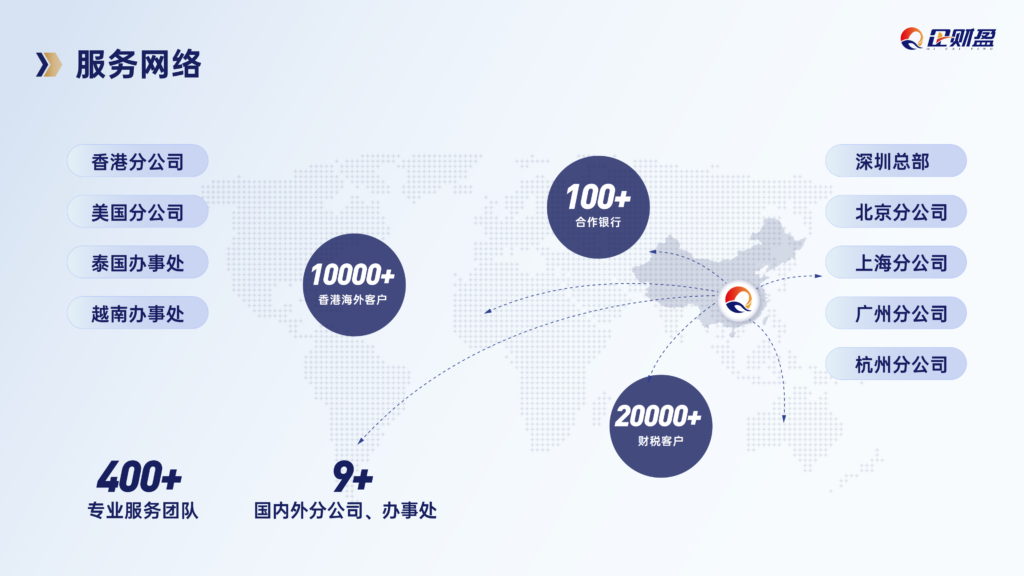
✔️ Global Presence: Headquartered in Shenzhen, with branches in Beijing, Shanghai, Guangzhou, Hangzhou, Hong Kong, Southeast Asia, and the United States
If you're considering registering a company or opening a bank account in Hong Kong, feel free to reach out to us—
Tags:
Guide to Opening a Bank Account in Hong Kong
Hong Kong Bank Account Opening Tips
Hong Kong Bank Account Opening
Recommended
Cross-border e-commerce B2B must see! Registered Hong Kong company stationed in the Ali International Station, really fragrant!
In today's globalized business environment, the cross-border e-commerce B2B model is rapidly emerging with its unique advantages. For many enterprises engaged in cross-border trade, choosing a suitable platform and registering an advantageous company are undoubtedly the key keys to open the door to the international market.
2024 Hong Kong Company Account Opening Tips! How to choose the right Hong Kong bank account?
Global anti-money laundering regulations are becoming more and more stringent, the banks to maintain an account of the sunk cost is getting higher and higher, not moving hundreds of millions of dollars in fines, so that the major banks to open an account threshold as well as the audit process high up, already have a Hong Kong company bosses, how to choose the Hong Kong bank to open a public account? How much does it cost and how to operate? Today to give you a detailed introduction to the Hong Kong company account how to choose, as well as the approximate costs required and other content.
Hong Kong company registration advantages + registration conditions + registration process to share!
If you want to start a business and develop overseas markets, registering a Hong Kong company is undoubtedly a very forward-looking choice. With its unique geographical location, sound legal system, low tax rate and open business environment, Hong Kong company has become a "sharp weapon" for many business owners to open up overseas markets. Why is it so important to register a Hong Kong company in 2024?