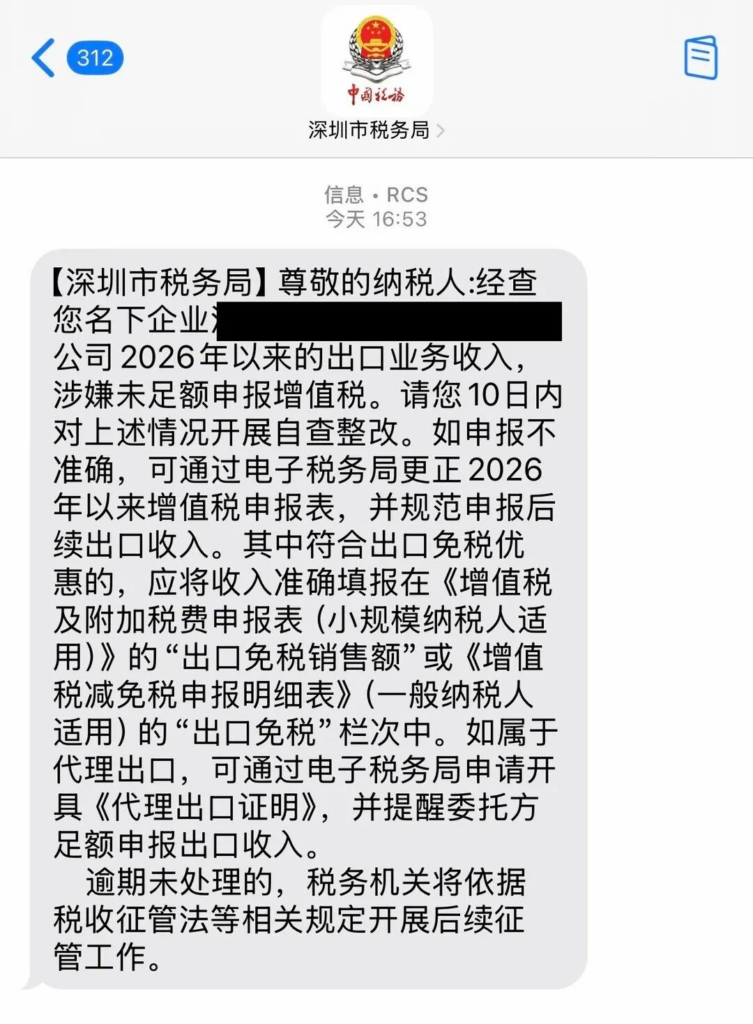
On September 1, a large number of sellers in Shenzhen received tax-related text messages stating: “Platform orders totaled 230 million, but only 170 million was reported—the difference indicates a risk.”
Published: September 9, 2026
On September 1, in Shenzhen’s Longhua, Bantian, and Bao’an districts—the three areas with the highest concentration of cross-border e-commerce activity—tens of thousands of sellers on Amazon, Temu, and independent websites reportedly received an official tax text message almost simultaneously.——
“Your company’s export revenue since 2026 is suspected of being underreported for value-added tax purposes. Please complete a self-inspection and make the necessary corrections within 10 days.”
It wasn’t a surge in orders—it was a flood of text messages. The cross-border e-commerce community was instantly in an uproar.
Many people's first reaction is: “Aren’t my export transactions tax-exempt? Why do I still have to file a tax return?”
This idea might be exactly why you received this text message.
If you’ve also received this text message and aren’t sure how to conduct a self-assessment or make corrections, or if you’re concerned that your architecture may have deeper-rooted issues, feel free to add us on WeChat and send us the basic details. Qicaiying will help you make a preliminary assessment—free of charge.
📱 WeChat: qcygscszk 📞 Phone: 18676749275
I. This text message is not a mass message.
Many people think this is a “mass message,” but that's not the case.
This text message isGolden Tax Phase IV System把 “GMV reported by the platform — customs declaration data — revenue self-reported by the company” After cross-checking the data from the three sources,A comparison alert that is automatically triggered when a discrepancy occursThe
According to industry rumors,If the difference exceeds 20%, an alert is triggered; if it exceeds 50%, the entity is directly placed on the priority audit list.. Although the authorities have not publicly disclosed a specific threshold, a “mismatch between reported income and platform data” in itself will trigger a risk alert.The
Starting in October 2025, Amazon has been submitting relevant data—including seller identities, transactions, revenue, and commissions—to domestic tax authorities on a quarterly basis, as required.. During the same period, the Guangdong Tax Bureau has collaborated with25 departmentsFacilitating the Sharing of Tax-Related DataThe
You were not “randomly selected”; rather, the system automatically detected an anomaly in the data and sent you a risk alert.
II. This type of architecture is the most prone to “crashing”
In this seller case study, the first to come under scrutiny were not those who failed to file taxes at all, nor those who filed accurately and in compliance—but rather a typical “Hybrid Architecture”::
A Hong Kong entity operates dozens of mainland storefront companies; all revenue is first deposited into a Hong Kong account before being transferred back to the mainland. The storefront companies file zero tax returns year-round, as do the Hong Kong companies, and they haven’t even completed ODI registration.The
This kind of structure is all too common in the cross-border industry—it’s convenient, easy to use, and offers flexible funding.. The core logic can be summed up in one sentence:The store is registered under a mainland company, with payments deposited into a Hong Kong company’s account; the store’s parent company does not report any income, and the Hong Kong company also files a zero-income return, with all profits remaining overseas.The
But this plan, after September 2026,It just isn't working at all.The
Why? Because this architecture is being besieged on all sides:
First Point: The Hong Kong shell has been penetrated. Information on Hong Kong corporate accounts is automatically exchanged with the Mainland tax authorities annually through the CRS.. State Council Order No. 837 has taken effect—if a mainland parent company holds a controlling stake in a Hong Kong company, has not filed for ODI approval, and retains undistributed profits in a Hong Kong account, this will directly triggerCFC (Controlled Foreign Corporation) Rules(Overseas profits are treated as dividends and subject to back taxes at a rate of 20%) andFines for Failure to Register with ODIThe
Page 2: Store and Company Under Investigation for Filing Zero-Income Tax Returns. The “alleged underreporting of value-added tax” mentioned in this warning text message is the core issue here.. Many business owners have the following financial practice: they report whatever amount they actually receive after the platform deducts commissions, advertising fees, FBA fees, and refunds.TheHowever, the tax bureau’s tax base is not the “net take-home pay,” but rather the “total order amount paid by the buyer.”. You report the net amount, and the system calculates based on the gross amount; the difference between the two is the risk.
Third Issue: Personal Account Receipts Are Subject to Penetration. Phase IV of the Golden Tax System has integrated data from the central bank and bank transaction records, and automatically consolidates multiple stores and accounts under the same actual controller.
Fourth Aspect: Multiple entities are identified in an overlapping manner. The store belongs to A, operations are handled by B, and customs clearance for the goods is handled by C—under this structure, a simple data check will ensure no one can pull the wool over anyone’s eyes.The
3. “Tax-free exports” does not mean “no need to file a declaration”
This Is the Most Common Misconception That Cross-Border Sellers Fall IntoThe
Many sellers believe that since export businesses are not required to pay value-added tax in the first place, it’s perfectly fine to simply enter “0” on the VAT return form.. Many small-scale sellers have long maintained “Tax-Exempt Exports = Zero Tax Return” Operating HabitsThe
However, according to tax regulations,The two are completely different things.The
According to Announcement No. 11 of 2026 issued by the Ministry of Finance and the State Taxation Administration, regardless of whether the transaction ultimately qualifies for a tax refund or tax exemption, the actual export revenue generated,All must complete their filings in accordance with the regulations.The
Not paying taxes does not mean you have no income.. If a company has a consistent history of exports, the customs system can access a large volume of customs declaration data; however, if the export sales exempt from VAT on the VAT return remain at zero for an extended period, and the data from multiple sources do not match, the system will automatically trigger a risk alert.The
IV. The cost of not addressing the issue is much higher than you might think
The text message this time said10-day self-inspection period. If the matter is not resolved by the deadline, the tax authorities will take follow-up collection and administration measures in accordance with the law.The
Proactively identifying and correcting issues on your own is the least costly approach. If you ignore a past-due payment, in addition to potentially incurring late fees, you may also faceAssessments, fines, and even the initiation of investigationsThe
If found guilty of tax evasion, VAT must be paid in arrears at a rate of 13%; corporate income tax will be assessed; late payment penalties will be 0.05 per day (annualized at 18.25%); and fines will be imposed in accordance with tax evasion regulations.0.5 to 5 timesThe
Since 2026, there have been several real-life cases in Shenzhen:
A cross-border company in Shenzhen faces back taxes and penalties9.89 million
A cross-border e-commerce company in Nanshan, Shenzhen, has been transferring its domestic operating profits on a large scale through a Hong Kong-based company,Recover 12 million
Shenzhen Jianmo Industrial Co., Ltd. received 3.0984 million yuan in payments through a personal bank account but reported only 20,000 yuan in revenue on its books,Tax arrears, fines, and late payment penalties totaled 679,900; the tax evasion case was referred to the police.
These aren't stories; they are real events that took place in Shenzhen.
V. What Should Sellers Do Now That They’ve Received the Text Message?
First, export the platform’s sales data and reconcile it item by item with the VAT data already filed to identify any discrepancies.TheAttention: You shouldn't be comparing the “take-home pay,” but ratherTotal Order Value on the PlatformThe
Second, if there are indeed omissions or underreporting, please correct the VAT returns for 2026 and later as soon as possible through the Electronic Tax Bureau.The
Third, if you confirm that your declaration is accurate but still receive an alert, gather supporting documents such as a breakdown of platform fees, refund records, and an explanation of exchange rate differences, and submit a written explanation to the tax authorities if necessary.The
Fourth, if you discover architectural issues during your self-assessment, do not make changes on your own. Hong Kong corporate restructuring, ODI filing, and historical financial statement review—each step involves professional judgment and specific operational procedures. A single misstep could lead to even greater risks.
VI. If You’re Also Worried
In the following situations, we recommend that you check your compliance status as soon as possible:
I received this tax alert text message—I don’t know how to conduct a self-inspection or how to make corrections
Currently using a “Hong Kong company + mainland store with zero tax reporting” structure—It's unclear how great the risk is.
The platform routes payments through a Hong Kong account, but the domestic company has not filed for ODI registration.—May have triggered the CFC rules
Operating multiple stores and entities, resulting in chaotic accounting—I don't know where to start
I'm not sure if my export revenue declaration is correct—I'd like to find someone to take a look at it for you
If you're unsure which risk level applies to your situation, you can add us on WeChat and send us your basic information—Qicaiying will help you make a preliminary assessment.
VII. What Can Qicaiying Do for You?
To address the tax compliance needs of cross-border e-commerce sellers, Qicaiying offers:
Support for Responding to Tax Alerts—If you receive a text message, we’ll help you make an initial assessment and develop a corrective action plan.
Review of Historical Records and Risk Assessment— Thoroughly review the accounts, invoices, and transaction records from the past 3 to 5 years to identify potential risk areas
Establishing a Compliance Framework for Hong Kong Companies— Hong Kong Company Registration, ODI Filing Guidance, Bookkeeping and Auditing, Offshore Exemption Applications
Export Tax Rebate Compliance Guidance—From document preparation to the application process, we’ll guide you through the entire official tax refund process
Compliance Assessment of Multi-Entity Structures—Helps you figure out “who owns the store, who manages it, and who handles customs clearance for the goods”
Who is this for?
Sellers who have received tax alert text messages—I don’t know how to conduct a self-inspection or how to make corrections
Sellers currently using the “Hong Kong company + Mainland store with zero tax returns” structure—It's unclear how great the risk is.
Sellers with multiple stores, multiple business entities, and disorganized financial records—I don't know where to start
Sellers who want to comply with regulations but are concerned about high costs—To understand the cost difference between “proactive handling” and “being investigated”
This text message from September 1 isn’t the end—it’s the beginning.
When it comes to cross-border tax compliance in 2026, there is no longer any leeway for claiming “lack of knowledge.”. All kinds of data leave a trail, so there’s no getting around reporting the income that needs to be declared.The
If you're unsure how to handle your situation, you can add us on WeChat and send us the basic details; Qicaiying will help you make a preliminary assessment.
📱 WeChat: qcygscszk 📞 Phone: 18676749275
statement denying or limiting responsibility
The content of this article is compiled based on publicly available industry information and tax policies. It is intended to provide policy interpretation and compliance risk alerts and does not constitute any tax, legal, or financial advice. The specific application of policies is subject to the determination of the competent tax authorities. If readers face specific tax issues, they should consult a qualified tax professional or the competent tax authority. Qicaiying assumes no legal liability for any losses arising from reliance on the content of this article.
Tags:
Tax Alerts
Shenzhen cross-border e-commerce
Cross-border e-commerce fiscal compliance
Tax Declaration
Financial and Tax Compliance
Recommended
Cross-border e-commerce B2B must see! Registered Hong Kong company stationed in the Ali International Station, really fragrant!
In today's globalized business environment, the cross-border e-commerce B2B model is rapidly emerging with its unique advantages. For many enterprises engaged in cross-border trade, choosing a suitable platform and registering an advantageous company are undoubtedly the key keys to open the door to the international market.
2024 Hong Kong Company Account Opening Tips! How to choose the right Hong Kong bank account?
Global anti-money laundering regulations are becoming more and more stringent, the banks to maintain an account of the sunk cost is getting higher and higher, not moving hundreds of millions of dollars in fines, so that the major banks to open an account threshold as well as the audit process high up, already have a Hong Kong company bosses, how to choose the Hong Kong bank to open a public account? How much does it cost and how to operate? Today to give you a detailed introduction to the Hong Kong company account how to choose, as well as the approximate costs required and other content.
Hong Kong company registration advantages + registration conditions + registration process to share!
If you want to start a business and develop overseas markets, registering a Hong Kong company is undoubtedly a very forward-looking choice. With its unique geographical location, sound legal system, low tax rate and open business environment, Hong Kong company has become a "sharp weapon" for many business owners to open up overseas markets. Why is it so important to register a Hong Kong company in 2024?