Attention Amazon Sellers! Amazon’s New BSA Regulations Are Now Officially in Effect! Sellers operating multiple stores or using Saiwei should conduct a self-assessment immediately.
Published: August 27, 2026
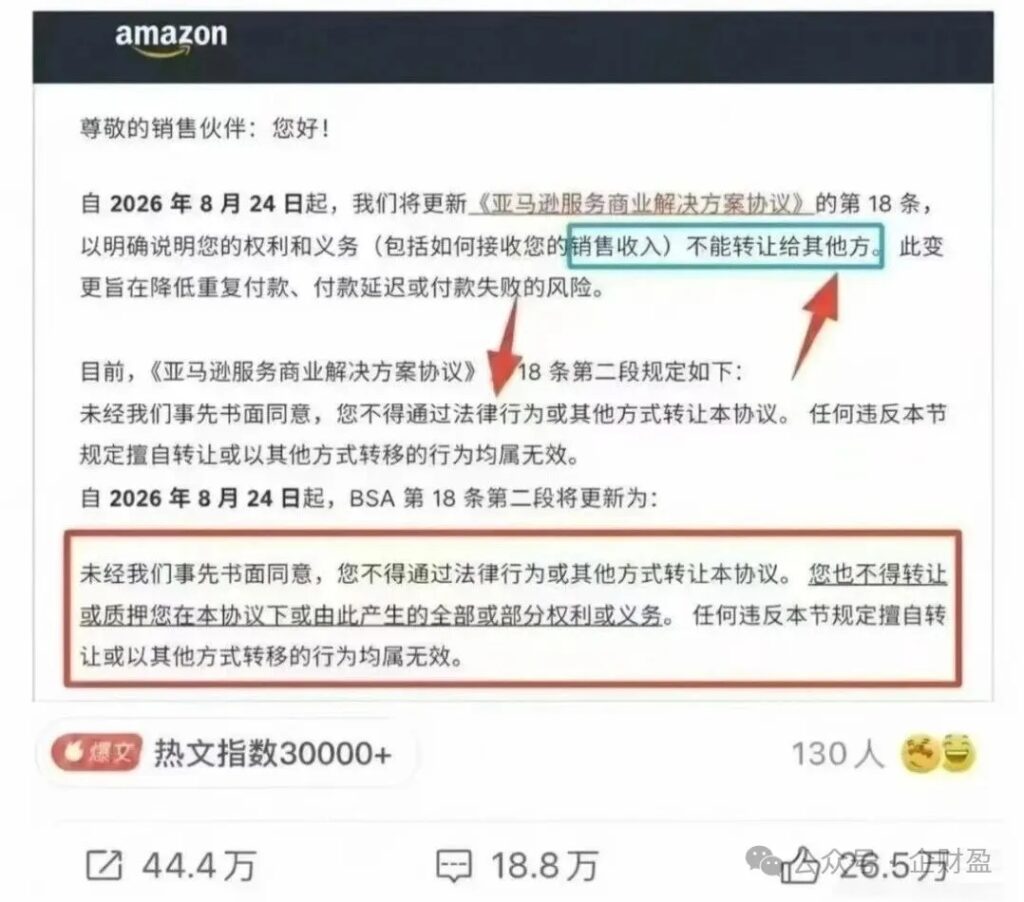
Amazon sellers are currently facing a “two-pronged attack”: On the platform side, Amazon has revised Article 18 of the BSA (Amazon Business Solutions Agreement) and it has officially taken effect—Without the platform's written consent, you may not transfer your store rights or use them as collateral, including any sales proceeds that have not yet been remitted to you.The
On the tax front, following the implementation of Document No. 15, platforms are required to submit store sales data to the tax authorities on a quarterly basis,Businesses that have consistently filed zero tax returns are now directly subject to data cross-checks.The
With these two developments coming together, sellers who operate multiple store networks, purchase stores for holding on their behalf, or use Saiwei-style funding structures will be the first to be affected. With a mix of accurate and inaccurate interpretations circulating online, this article from Qi Cai Ying clearly explains the logic behind the rules, provides a comprehensive overview of the Saiwei model, and outlines available options—so you can determine which category you fall into.
If you have any questions regarding financial and tax compliance for cross-border e-commerce, you can contact Qicaiying’s online customer service directly (WeChat: jxhqcy890 / Mobile: 16625410105) for assistance.
.
01 New Platform Rules: What Exactly Has Changed in Article 18 of the BSA?
Put simply, this revision boils down to two things:
Non-transferable:You may not transfer your store rights to another party without Amazon’s official written consent;
Cannot be used as collateral:You may not use store assets (including sales proceeds that have not yet been received) as collateral to borrow money.
Note that this has nothing to do with “how you spend your money,” but rather with the ownership of the store’s rights and interests on the platform itself. Many sellers fall into this trap precisely because they confuse these two completely different matters.
One important rule—please be sure to remember:
Before the funds have even been deposited into the store’s corporate account, an agreement is signed in advance stating that “future payments will go to the Hong Kong company/parent company” = If you transfer your rights early, Amazon won’t recognize any contract you signed privately—that’s crossing the line..;
The payment has been transferred in full to the account of the company registered for the store. After that, the payment for goods and service fees will be made in accordance with the contract = If you're operating normally, the new regulations won't affect you.The
In addition, this rule falls underTrigger-Based Risk Control...It doesn't mean stores will be shut down en masse right away: The platform won't specifically contact you while your store is operating smoothly, but as soon as any of the following scenarios occurs—a secondary review/KYC, a performance appeal, a change to your payment account, or a random platform audit—the new regulations will serve as the basis for judgment. The risk hasn't gone away; it's just hanging over your head.
.
02 Multi-Store Sellers: Identify Which Situation Applies to You—Two Scenarios
Legitimate, native store clusters: Virtually no impact
A single owner controls multiple independent companies, with each store having its own business license, payment account, and brand—all of which are fully aligned. Such sellers are minimally affected by the new regulations. The only change is that, going forward, if they wish to transfer an entire store to another corporate entity, they must submit a complete set of authentic merger and reorganization documents and obtain written permission from Amazon. If the change involves only a change in the legal representative or a company name change—with the Unified Social Credit Code remaining unchanged—then they are not affected.
Buying a Store + Nominee Ownership: The Risks Are Always Lurking
Bulk purchase of established stores created by others; the business license remains in the original company’s name, but you are the one actually running the business and making a profit. Both parties sign a private transfer or nominee agreement—This agreement is not valid on Amazon's end.. Once a review is triggered, the platform can directly determine that an account has been transferred without authorization: it will revoke sales privileges and freeze funds, and it is extremely difficult to appeal this decision; if the original registered company becomes involved in a debt lawsuit, judicial authorities can also directly freeze the store’s funds, making it very difficult for the actual operator to mount a defense.
There are very few options for a remedy: either 100% acquires the original company’s equity (conducting due diligence on dozens or even hundreds of stores one by one—a bulk approach won’t work); or file a case to apply for a change of entity (without a genuine M&A background, this will likely be rejected and flagged as high-risk).
Two guiding principles for managing existing stores held in trust:
Do not acquire any more stores of the same type;
Try to avoid triggering any audits as much as possible, while simultaneously planning for compliance-related corrective actions.
.
03 A One-Minute Overview of the Suntech Model: The Backstory
The SAIWEI model originated from the compliance structure established when the mass-distribution retailer “SAIWEI Times” went public (retail store company + domestic export company + operating company + Hong Kong company, forming a closed-loop system for the three flows). The key factor that led to regulatory approval at the time wasNo Loss of Tax RevenueThe
Over time, several versions emerged, but all you need to remember are these three sentences:
Why is Savi 1.0 dangerous:Zero-reporting for store companies, with proceeds directly pooled in Hong Kong—following the issuance of Document No. 15, there has been a significant discrepancy between the sales data reported by the platform and the zero-reporting figures, which the tax authorities can spot immediately upon comparison; the fact that the stores do not handle any funds also directly crosses the red line set by BSA18 regarding the “early assignment of rights to proceeds”;
What Is Cost Allocation?:While the overall structure remains unchanged, costs are allocated to each store based on their share of sales, and taxes are reported and paid locally, thereby resolving the “zero-reporting” deadlock—this is currently still in the pilot phase, and businesses must proactively coordinate with their local tax authorities;
The Essence of SAIWEI 2.0:A Hong Kong company actually resells the goods to a retail company, which recognizes revenue based on the actual transaction; the proceeds are first deposited into the retail company’s corporate account before being used to pay for the goods—this step is precisely the safety net provided by the new BSA18 regulations.
The specific details of the transaction (the six-step trading process, pricing markups, and tax treatment) are quite lengthy, so I won’t go into them here,If you'd like to learn more about the full version, feel free to contact Qicaiying directly.The
You can add Qicaiying's online customer service (WeChat: jxhqcy890 / Mobile: 16625410105), and we will arrange for a professional manager to provide tailored answers to your questions.
.
04 Identify Which Version You Have: Three Types of Savi—Find the One That Fits You in One Sentence
There are actually three types of “Saiwei” products circulating on the market, each with vastly different outcomes. You can quickly check for yourself:
Saiwei 1.0 (Pooling Model):Zero-reporting for the store, funds deposited directly into a Hong Kong account, and the store’s company never sees the money—stepping on landmines on both ends,Under the new regulations, no new projects should be built, and existing ones should be brought into compliance as soon as possible;
Knockoff Version 2.0:They copied just one organizational chart; payments aren’t deposited into the store’s corporate account; ownership of the goods is transferred solely through staged photos; and the agreement even states that “proceeds belong to the group”—this is “shell company swap” 1.0,This directly violates the new regulations' red lines, so corrective action must be taken immediately;
Official Version 2.0:Ensure that the actual trade chain is fully operational, and that payments are first deposited into the store’s corporate account before any external payments are made—this way, neither the platform nor the tax authorities cross any red lines,It is currently one of the preferred approaches for balancing the two regulatory frameworks.
Four Basic Principles for Running Genuine Version 2.0:
The proceeds must ultimately be withdrawn to the corresponding store’s corporate bank account; do not transfer them directly to Hong Kong from the payment account;
The contract should only state, “The store will pay the purchase price to Hong Kong after receiving payment,” and must not include any wording such as “the rights to the payment belong to Hong Kong/the parent company”;
Do not use future payments from the store as collateral for a loan—this is expressly prohibited by the platform;
Retain all purchase and sales contracts, pro forma invoices, overseas warehouse receipt documents, proof of ownership, FBA inventory records, and pricing documentation for related-party transactions—no matter how well-designed the organizational chart is, if you can’t produce authentic supporting documents, it won’t pass audits on either side.
.
05 How to Choose: Find the Right Fit Based on Size
Small sellers (fewer than 5 stores and annual revenue under 30 million):We do not recommend making any changes. Stick with your current structure and ensure your documentation is complete—including the cost and expense allocation statement, proof of self-filed 100% customs declarations, proof of full tax payment for 100%, and the Hong Kong company’s ODI filing. Proactively communicate with your tax authority to explain that “all funds have been repatriated and no taxes have been underpaid”;
Large sellers (with dozens or even hundreds of stores):If you have to choose between “Pooling and Allocation” and “Saiwei 2.0,” we do not recommend using 9810. If you want to keep things simple and manage your funds, prioritize exploring the “Pooling and Allocation” method; if the tax authority explicitly requires you to file by store, then switch to the “Saiwei 2.0” method;
Changes required by the tax authorities:First, check with your local tax authority to see which method is feasible. If you switch to Version 2.0, the Hong Kong company’s chain of evidence for “overseas procurement” must be authentic—including pro forma invoices, purchase contracts, and shipping documents. Not a single one can be missing.
The Final Deadline: True Compliance vs. False Compliance
No matter which path you choose, what regulators take issue with is never the business model itself, but rather “fake compliance”—merely copying the structure of multiple stores and a Hong Kong shell company, while shipping goods via export invoices, withdrawing funds to personal bank accounts, and failing to repatriate profits.
The Five Bottom Lines of True Compliance:
货——100% self-declaration, eliminating the practice of "buying" export declarations;
票— The procurement front-end team 100% obtained the input invoices;
钱——Profits of 1,001 TP3T are repatriated to China and taxes are paid in full;
壳—Hong Kong companies do not retain profits that are out of line with their operational efficiency;
账—Funds are transferred via account 100% for business purposes; personal accounts are not involved.
BSA18 and Document No. 15—one governing the attribution of rights on the platform side, the other governing data reconciliation on the tax side—these two approaches are bringing an end to the era of “building architecture based on gut feelings.” Whether the payment collection process is compliant, whether contract wording crosses any lines, whether business documentation is credible, and whether store reporting data matches up—these four factors determine whether your store will be deemed “operating normally” or classified as “illegal transfer” or “false reporting” during the next audit and data comparison.
Sellers facing inventory risks should not delay. The window of opportunity to address these issues is always least costly before the risks come to a head.
If you're struggling with these issues, feel free to reach out and talk to us. For inquiries, contact Qicaiying’s online customer service (WeChat: jxhqcy890 / Mobile: 16625410105). The specific services we offer include:
Cross-Border E-Commerce Tax and Financial Compliance Assessment (Risk Assessment for Store Networks, Nominee Holdings, and Saiwei Structures)
Design of a Remediation Plan for Cash Flow Channels (Centralized Collection of Receivables, Ensuring Contract Language Compliance)
Saiwei 1.0 Rectification, Collection, and Allocation Implementation Guidance (Including Communication with the Tax Authority and Establishment of a Chain of Evidence)
The Complete Process for Setting Up the SAIWEI 2.0 Architecture (Transfer of Title, Pro Forma Invoices, and Pricing Markup Design)
End-to-End Export Tax Rebate Services, ODI (Overseas Direct Investment) Filing
Sole Proprietorship Structure Design and Risk Isolation · Dedicated Team Support + Error Compensation Mechanism
Clients who are suitable for consultation:
I have some stores held in trust and some older stores I bought, but I'm not sure what to do with them.
Currently running Saiwei 1.0 or a knockoff 2.0 version; payments aren't being deposited into the store's corporate account.
Your store has consistently reported zero revenue, and you have received a statistical report from the tax authority or are concerned about data-matching alerts
I want to use the official 2.0 version or the pooling and apportionment method, but I'm not sure how to structure the contract and cash flows to ensure compliance.
Compliance comes at a cost, but the price of operating without it is even higher.Compliance transition is better sooner rather than later, the earlier the layout, the lower the cost, the more stable the development.
If your business is currently at one of the following stages:
[Startup Phase] Annual revenue < 20 million:Concerned about zero-reporting, payments received through personal accounts, or the impact of the Golden Tax Phase IV initiative?
[Growth Stage] Annual Revenue: 20 million–100 million:Are you struggling with export tax rebates, unaccounted-for receipts, and financial disarray?
[Maturity Stage] Annual Revenue > 100 million:Thinking about equity structure, inventory optimization, and IPO preparation?
We have the right solutions and practical experience for all of these situations. If you haveHong Kong Company Registration, Bank Account Opening, Annual Audit, Financial and Tax Compliance, and Setting Up Structures for Import and Export Operationsand other needs.Sellers who require a case-by-case assessment based on the number of stores, sales volume, supply chain conditions, and existing business entities, you can contact Qicaiying's online customer service (WeChat: jxhqcy890 / Mobile: 16625410105). When communicating with us, we recommend that you first prepare basic information regarding your platform, business entity, procurement, exports, and payment collection. Based on this information, we will assign a professional manager to provide tailored answers to your questions.
Tags:
Amazon Store Network
An Analysis of Amazon's New Policies
Saiwei 2.0
tax risk
zero declaration
Multi-Store Sellers
Amazon Compliance
Safeway model
Safeway Model Compliance
Amazon seller
Cross-border sellers
Recommended
Foreign funds repatriated this way are taxed at only 1% and are compliant!
How to collect overseas trade funds? Is there a safe and compliant way to operate? There are funds in foreign countries, usually individuals or companies in business transactions with foreign companies and generate revenue, this situation in fact, there are ways to comply with the legal operation, and the return of the tax rate is extremely low! Before we provide the method, let's first understand how most people do it?
Cross-border e-commerce Amazon small team annual income of 20 million, how to do financial and tax compliance?
Amazon four people small team annual income of 5 million, the main body is a general taxpayer but did not do the tax rebate, withdrawals to the boss's private card, that now, want to develop more products, if the collection of more than 20 million, how to comply with the collection to do this fiscal compliance?
Export tax refunds are difficult and complicated?The latest export tax refund filing conditions process in 2024!
For some newly established or just started to have export business of foreign trade enterprises, the whole process of export tax rebate declaration is in a state of ignorance, do not know how to handle, where to go, the process and so on. In this article, we organize the process from the filing of export tax rebate (exemption) to the declaration of export tax rebate, as well as the latest policy in 2024.