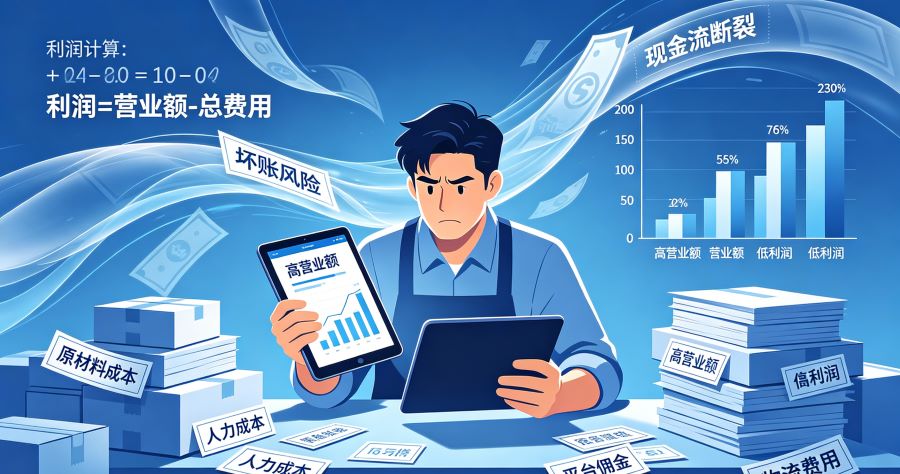
The company has revenue of 30 million, but profits are less than 1 million. After filing your tax returns in compliance with regulations, are you actually making a profit or a loss?
Published: July 20, 2026
QCYAs a professional one-stop business service platform, we are committed to providing our clients with high-quality services—including company registration in mainland cities such as Beijing, Shanghai, Guangzhou, Shenzhen, and Hangzhou; cross-border e-commerce services; Hong Kong company registration; offshore company registration; bookkeeping and tax filing; annual reviews and audits; corporate bank account opening; financial and tax compliance; equity structuring; ODI filing, cross-border e-commerce services, Hong Kong residency, immigration, and study abroad, among other high-quality services, to support the globalization of businesses.
Please contact me to request materials and a quote (WeChat/phone: JXH23314).
Mr. Liu, who runs a building materials wholesale business, came to see us. He pulled out his phone and showed me his financial statements for the entire year:
“Our company’s business turnover this year was 30 million, but when we did the year-end calculations, our net profit was less than 800,000—less than what I made last year when our turnover was 20 million. The tax authorities require us to file our returns in full compliance. Should I report such a low profit honestly? If I do, will we be audited? Does this count as a profit or a loss?”
In fact, many industries are currently experiencing this kind of “artificial growth”—businesses appear to be booming, with revenue flowing in steadily, but when it comes time to calculate profits, there’s hardly anything left, leaving them stuck at the compliance reporting stage with no clear way forward. Today, I’ve compiled the key points and recommendations I’ve identified; business owners facing similar challenges can see if this applies to them.
One,Why Is Revenue High but Profits Not Increasing?
In fact, many business owners haven’t figured out for themselves why, even though they’ve secured a large number of orders, the money hasn’t made it into their pockets. By breaking down the situation of this building materials wholesaler, we can thoroughly explain this type of problem.
He is in the regional building materials distribution business, acting as a link between upstream manufacturers and downstream renovation companies. This is a typical low-margin industry, and in this volume-driven business model, profits are inherently very thin.
In addition to the industry’s inherently low profit margins, there are two other common factors that further drive profits down:
First,Hidden costs haven't been fully accounted for, which makes profits appear artificially high, but the actual earnings are lower.. Many small and medium-sized business owners face numerous miscellaneous expenses for which they cannot obtain valid invoices, such as labor costs for hiring temporary workers to move goods, referral fees paid to clients, and miscellaneous transportation expenses.
Second,Fixed costs account for too large a proportion of total costs; as revenue increases, costs rise along with it.Take e-commerce live-streaming advertising, for example: to sell 10 million in merchandise, you’d need to spend 2 million on advertising; to sell 30 million, the advertising budget would rise to 6 million. While revenue triples, so do advertising costs. This model—where “revenue growth is accompanied by a proportional increase in costs”—is a classic example of generating buzz without actually making a profit.
Two,Compliance Reporting: How to Calculate Profits and Losses
If you underreport income or inflate expenses to make it appear as though your profits are low so you can pay less in taxes, the risks you’re creating will actually end up costing you more in the long run.. The regulatory logic behind the Golden Tax Phase IV initiative is now completely different from before; high turnover with low profits is an anomaly that the tax authorities are focusing on. Many business owners believe that “compliance means paying more taxes,” but if you think about it the other way around, compliance is actually what helps you save on the taxes you’re supposed to save on.
So the conclusion is actually quite clear:As long as your business operations are legitimate and you file your taxes truthfully and in compliance with the law, you’re coming out ahead; if you engage in non-compliant practices out of a hope to get away with it, you may appear to be paying less in taxes, but the potential losses resulting from the risks involved are the real loss.The
Three,First, get the books in order to determine the true profit.
The first step in any optimization effort is to get your books in order. For many companies, the problem isn’t that their profits are actually low—it’s that their books aren’t kept correctly, which leads to inaccurate profit figures. Here are three specific steps you can take:
First.Record all costs for which you can obtain receipts as expenses; do not leave any gaps.The
Second.Reconcile transaction records with invoiced revenue to ensure consistency among the three flows.The
Third.Distinguish between fixed and variable costs, and cut out unnecessary expensesThe
Four,Comply with regulations to enjoy tax benefits and reasonably reduce your tax burden
Once you’ve sorted out your books, the next step is to comply with regulations and take full advantage of the tax incentives you’re entitled to. Don’t miss out on benefits you’re clearly eligible for and end up paying more taxes unnecessarily. Here are two of the most common—and most easily overlooked—incentives:
First,Be Sure to Take Full Advantage of Income Tax Incentives for Small and Micro EnterprisesThe
How can you make the most of this? If you have multiple business segments, consider splitting them into separate legal entities, ensuring that each entity keeps its profits within the preferential tax bracket. This will help reduce your overall tax burden.
Just a reminder: When splitting up business operations, make sure it’s a genuine business split. Don’t split them up just for the sake of splitting them, and definitely don’t set up shell companies to issue fake invoices—that’s a violation of the rules and will only cause problems.
Second,Be sure to claim all eligible deductions in a timely manner so you don’t waste your deduction allowance.The
In addition to standard cost deductions, there are many other deductible items. For example, companies that hire people with disabilities can receive reductions in the disability employment guarantee fund and immediate VAT refunds; for R&D expenses, even if you’re only making minor product improvements, you can still claim an additional deduction if the expenses meet the eligibility criteria; Additionally, social insurance contributions, housing provident fund contributions, and employee welfare expenses can all be deducted before taxes in accordance with regulations. By claiming all eligible deductions and making all necessary adjustments, you can reduce your taxable income.
Five,Establish a regular self-inspection process to nip risks in the bud
Finally, it’s essential to develop the habit of conducting regular self-inspections. Businesses with high turnover and low profit margins are already a key focus of regulatory scrutiny, and identifying and addressing issues proactively is far less costly than having to take corrective action after an inspection. Here are two simple and practical areas to focus on during your self-inspections:
First.Conduct an annual self-audit focused on specific tax categories, with an emphasis on verifying the consistency between revenue and expenses.The
Second.Don’t adopt the mindset that “once you’ve filed the report, you’re off the hook,” and certainly don’t think that “once you’ve deregistered, you can pass the buck.”The
Finally, let’s return to the question posed by the building materials business owner at the beginning. My advice to him was: Declare your income honestly. If you earned 800,000 and paid 40,000 in taxes, you’d end up with 760,000—that’s a real profit; If you conceal your income to adjust your reported profit and end up paying tens of thousands less in taxes, but risk a fine of several million, that’s a real loss.
If you, too, are facing—taxation servicesIssues with Compliance Reporting(math.) genusScan the QR code to add our online customer service representative (Microsignal:(JXH23314)(math.) genusBased on your specific situation, we will arrange for a professional consultant to address your questions and provide one-on-one, end-to-end compliance solutions.
Tags:
Compliance filing
Financial and Tax Compliance
Recommended
Cross-border e-commerce B2B must see! Registered Hong Kong company stationed in the Ali International Station, really fragrant!
In today's globalized business environment, the cross-border e-commerce B2B model is rapidly emerging with its unique advantages. For many enterprises engaged in cross-border trade, choosing a suitable platform and registering an advantageous company are undoubtedly the key keys to open the door to the international market.
2024 Hong Kong Company Account Opening Tips! How to choose the right Hong Kong bank account?
Global anti-money laundering regulations are becoming more and more stringent, the banks to maintain an account of the sunk cost is getting higher and higher, not moving hundreds of millions of dollars in fines, so that the major banks to open an account threshold as well as the audit process high up, already have a Hong Kong company bosses, how to choose the Hong Kong bank to open a public account? How much does it cost and how to operate? Today to give you a detailed introduction to the Hong Kong company account how to choose, as well as the approximate costs required and other content.
Hong Kong company registration advantages + registration conditions + registration process to share!
If you want to start a business and develop overseas markets, registering a Hong Kong company is undoubtedly a very forward-looking choice. With its unique geographical location, sound legal system, low tax rate and open business environment, Hong Kong company has become a "sharp weapon" for many business owners to open up overseas markets. Why is it so important to register a Hong Kong company in 2024?