Another Major “Fictitious Export” Case Uncovered in Shenzhen! 6.31 Million in Tax Fraud, 12.3 Million in Fines! How Can Fictitious Export Operations Transition to Compliance?
Published: July 16, 2026
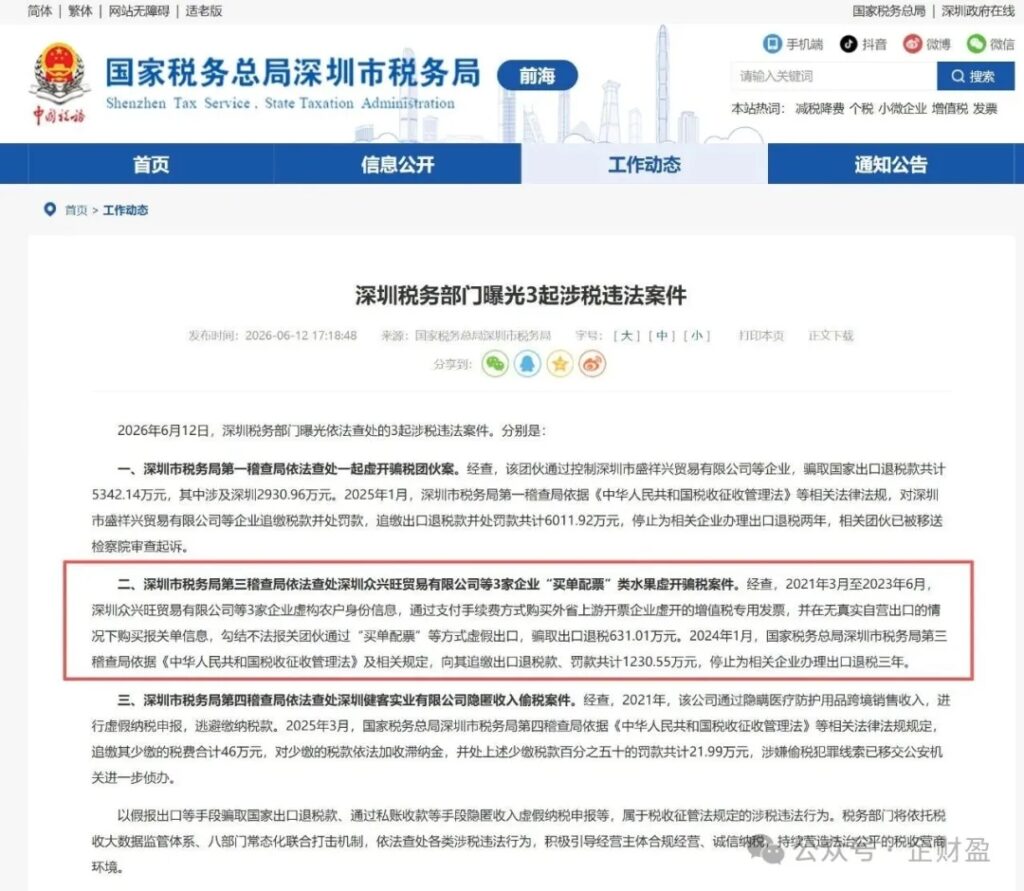
Last month, three Shenzhen-based companies—Zhongxingwang, Haojijie, and Chuanhuisheng—staged a ”fruit export” scam: they declared exports worth 527 million, but the actual foreign exchange receipts amounted to less than 40 percent of that figure. Upon further investigation, it was discovered that:Input invoices totaled only 200 million, leaving a shortfall of 300 million; the customs-declared goods—”wooden furniture”—did not match the ”plastic products” listed on the actual bill of lading; the foreign exchange received was transferred in full to the invoicing party on the same day, then funneled through dozens of private accounts before ending up back in the company’s own pockets.
(Image source: Official website of the Shenzhen Tax Bureau of the State Taxation Administration)
Joint Tax and Public Security Crackdown: Tax refunds totaling 6.31 million were fraudulently obtained; the total amount recovered and fines imposed amounted to 12.3055 million. Tax refund processing has been suspended for three years. The suspect has been transferred to the procuratorate.
In the first half of this year, in Shenzhen, Dongguan, and Guangzhou alone, the number of cross-border sellers investigated exceeded2,000. The 90% scheme involves export invoicing combined with off-the-books collections. The average back taxes and penalties range from 800,000 to 3 million; in some major cases, they can reach tens of millions or even hundreds of millions.
If you’re still handling export invoicing but want to transition to a compliant process and aren’t sure how to proceed, feel free to scan the QR code to contact Qicaiying’s online customer service (WeChat ID:jxhqcy890 / Mobile: 16625410105) 👉Based on your specific situation, we’ll assign a professional consultant to address your questions and provide one-on-one, end-to-end compliance solutions.
01How does the tax authority currently audit export invoices?
To be honest, export transactions involving advance payments did used to be a bit of a ”gray area.” It wasn’t easy for the tax authorities to investigate them—data wasn’t shared, and the chain of evidence was incomplete, so they often turned a blind eye.
But it’s now 2026. Phase IV of the Golden Tax Project is in full swing, electronic invoices have been rolled out across the board, and e-commerce platforms have begun reporting seller data to the tax authorities. Every transaction you make now is recorded in the systems of three government agencies.
Specifically, the tax authorities are currently auditing export invoices forSeven Approaches. It sounds like a lot, but you don’t actually need to get all seven right—matching two or three is enough to open a case.
① Incorrect HS codes
Just think about it: a typical foreign trade company usually exports only a few specific categories of goods. But on the customs declarations for export invoices, one day it’s clothing, the next it’s machinery, and the day after that it’s electronics—you can tell something’s off at a glance. The tax authorities think the same way.
② A shell company can’t hold up
When the company that handled your customs declaration is summoned by the tax authorities, it will simply say, ”I didn’t export anything; the goods aren’t mine—I just collected a few hundred yuan in agency fees.” The problem is, your company’s name is listed on the customs declaration form. According to tax law, ”whoever exports must file the declaration and pay the tax.” If you claim the goods aren’t yours, did you file the declaration? No, you didn’t. So who will the tax authorities go after? They’ll go after the actual owner of the goods behind you. Some local tax bureaus have already sent letters directly to freight forwarders, stating: ”We hereby request your company’s assistance in providing the name, business address, contact person, and contact information of the actual exporting enterprise.” Do you really think the freight forwarder will take the fall for you?
③ The logistics tracking information does not match
The goods were shipped from a warehouse in Beijing, but the customs declaration form listed Shenzhen as the port of exit—a shipment headed north ended up traveling across nearly half of China to exit via the south. The tax authority’s system immediately flagged this as suspicious.
④ The invoices on the purchasing side do not match
The customs declaration listed ”electronic products,” but the purchase invoice listed ”plastic toys.” The documents and the goods didn’t match up, so the discrepancy was immediately obvious when they were compared.
⑤ Cash flow has been disrupted
This is the most critical issue. Customs data is now linked to the State Administration of Foreign Exchange’s data—you declare $1 million worth of goods, but whose pocket did that $1 million end up in? Company A, listed as the importer on the customs declaration, didn’t receive a single cent in foreign exchange, yet the owner’s personal account shows large withdrawals from PayPal and Western Union. Banks are keeping a close eye on this, too. If an individual converts more than $50,000 in foreign currency annually, they must explain the source of the funds—how are you going to justify that? The AI analysis under Phase IV of the Golden Tax System tracks every transaction in your account. If it detects that ”export revenue hasn’t been deposited into the company’s official account,” it’s classified as tax evasion—resulting in back payments of VAT (13%) and corporate income tax (25%), plus fines ranging from 0.5 to 5 times the amount owed.
⑥ When a teammate gets into trouble, you’re the first to be implicated
If the company that handles your customs clearance ever gets investigated for issuing fraudulent invoices, the tax authorities will review every business that has ever worked with them. Are you sure your freight forwarder can withstand an investigation?
⑦ The agency fees are ridiculously low
In most industries, agency fees account for a certain percentage of export revenue. The agency fee you’re paying is only one-thousandth of the export amount—or even less—which is far below the industry average. When the tax authorities see this figure, their first reaction is: This company is either inflating its invoices or engaging in fake exports.
Let’s be blunt: when it comes to export invoicing, the regulatory environment in 2026 is completely different from what it was two years ago. It used to be a case of ”blind spots under the lamp,” but now that data from the three departments has been integrated, everything is ”out in the open.” You might think, ”It’s not just me doing this,” but the truth is, it’s just not your turn yet.
If you’re still handling export invoicing but want to transition to a compliant process and aren’t sure how to proceed, feel free to scan the QR code to contact Qicaiying’s online customer service (WeChat ID:jxhqcy890 / Mobile: 16625410105) 👉Based on your specific situation, we’ll assign a professional consultant to address your questions and provide one-on-one, end-to-end compliance solutions.
.
02Illusion: I’m small, so no one will target me.
I often hear sellers say, ”My annual revenue is only a few million—the tax authorities wouldn’t bother targeting me.”
The list posted in the Longhua District Tax Bureau’s service hall consists largely of small and micro enterprises. The tax bureau’s approach to investigating ”buy-and-sell” exports is not about “catching the big fish,”That is“Clear Backlog”TheThe system assigns the case to whoever’s customs declaration data is flagged as abnormal.
There's another point in time you might not have realized.
Starting in October 2025, platforms such as Amazon, Taobao, and Douyin have already begun reporting seller identification and revenue data to the tax authorities.As soon as the annual tax settlement period ended on May 31 of this year, risk control lists were issued nationwide in batches. Cross-border sellers generating revenue in the millions and tens of millions have been successively flagged for risk control or audits.
The audit process has also changed. In the past, case officers would work their way up through the ranks, but now the General Administration and provincial bureaus directly assign risk cases with little to no leeway. As soon as the system flags a risk, an audit is launched.
At the end of the day, it’s not a question of ”whether you’ll be investigated,” but ”when it will be your turn.”
.
03Lesson: Don’t focus on how much money you’ve saved; focus on how much you’ll have to pay if you get caught.
The essence of export invoicing can be summed up in one sentence: avoiding taxes and cutting costs.
But that’s not how it works. Let me give you a comparison—take a look for yourself:
sports event
buy orders to sell goods (e.g. for export)
Compliance Program
Procurement costs
No invoice issued; unit price is 120 yuan
Issue an invoice at a unit price of 132 yuan (plus 10 points).
Value-Added Tax (Export Stage)
Detected: Treated as domestic sales; pay back 13%
Compliant Export, 0% (Tax Rebate) or Tax-Exempt
corporate income tax
Caught: Must make up 251 TP and 3 T, plus a fine
Pay as usual based on profit
How is foreign exchange collected?
Underground Money Transfer Services or Private Accounts: The Risk of Card Freezes
Legally Received Foreign Exchange Through Corporate Accounts
Criminal Liability
If the amount of tax evaded is large, you'll go to jail.
There is no such risk
Additional Costs
Late payment fee (calculated daily) + a fine of 0.5 to 5 times the original amount
None
Hidden Costs
Afraid to take out loans, afraid to raise capital, afraid to expand
You can raise capital, go public, and build a brand
That's just what's out in the open. What's truly terrifying is what lies hidden.
You’ve worked hard for several years in cross-border e-commerce, accumulated several million in profits, and feel pretty good about yourself. Then one day, out of the blue, you receive a notice from the tax authorities—not asking you to pay this year’s taxes, but to pay back taxes from several years ago, plus late payment penalties and fines. Those several million could vanish in the blink of an eye.
.
04I don't want to pay for the export anymore. What should I do next?
You might be reading this and thinking, “I don’t want to keep paying for export invoices either.” But my situation is a bit tricky—I can get invoices for some goods but not for others; I have multiple stores, with several business entities located in different cities; and my business volume is neither large nor small. How exactly should I go about ensuring compliance?
Based on our experience with hundreds of sellers, I’d like to offer three approaches for your consideration. These aren’t one-size-fits-all solutions—choose the one that best fits your specific situation.
.
Option 1: Saiwei 2.0 — The Most Practical Solution for Multi-Store Sellers
What Kind of Sellers Are Suitable:They operate multiple stores, have annual revenue of 5 million or more, and have already registered—or are willing to register—a Hong Kong company.
Simply put, here's how it works:
A domestic export company uses the "0110" general trade procedure to formally clear the goods through customs for export and sell them to its own Hong Kong subsidiary.
The Hong Kong company then ”resells” this shipment to your various store companies.
The store’s company confirms its sales revenue—there is revenue and cost recorded in the books, and the data reported by the platform matches the data submitted in the tax return.
Why It's Worth Considering:
Following the requirement in Document No. 15 for platforms to submit data, the biggest risk is that ”the data does not match up.” Saiwei 2.0 directly addresses this issue—store companies no longer file zero-reporting returns.
Local tax bureaus are now able to report their figures without difficulty, and the issue of tax revenue allocation across regions has been resolved.
Retail stores owned by Hong Kong companies are currently not subject to the reporting requirements under Document No. 15, offering greater compliance stability.
.
Option 2: Have a Hong Kong company directly operate the store — isolating risk at the source
What Kind of Sellers Are Suitable:It’s a relatively large company with annual revenue exceeding 20 million, and we want to establish a long-term, compliant structure so we don’t have to worry about policy changes every year.
Simply put, here's how it works:
Use a Hong Kong company directly as the entity that owns the store on Amazon or other e-commerce platforms
A domestic export company uses the 0110 code to formally clear customs for goods sold to a Hong Kong company.
Establish another service company in mainland China to provide Hong Kong companies with support services such as operations, design, and supply chain management, and charge service fees.
Why It's Worth Considering:
Stores owned by overseas companies are currently not included in the scope of tax-related information reporting required by the platform established under Document No. 15. Fundamentally, there is no issue of ”data comparison.”
Physical Separation of Domestic and Overseas Operations—”Overseas Sales, Domestic Services,” with the Two Channels Clearly Distinct
You might be surprised to hear this:Listed giants like Suntech and Anker Innovation use this very architecture.
.
Option 3: Purchase with an invoice → Handle customs clearance and tax refund yourself
What Kind of Sellers Are Suitable:Upstream suppliers can issue 13% VAT special invoices, regardless of order volume.
Simply put, here's how it works:Obtain the necessary import and export licenses, and file customs declarations for exports under your company’s name; legally receive foreign exchange through your company’s account and file export tax refund claims in accordance with regulations; ensure that business flows, cash flows, and document flows are all clearly documented.
This approach is the ”cleanest”—it’s fully compliant, and getting any refundable taxes back is a benefit in itself; plus, it’s a viable path for both building a brand and raising capital.
.
Regarding Situations Where ”Invoices Cannot Be Obtained for Purchases”
To be honest, most cross-border sellers face this problem—factories either refuse to issue invoices or charge an additional 10% tax when they do, which eats up all their profit.
If this is your situation, there are two approaches you can consider:
For annual exports of less than 5 million, you may consider combining the 1039 Market Procurement Trade program with a fixed-rate income tax assessment. However, it’s important to note that the 1039 program has restrictions on product categories—not all products are eligible.
For companies with annual exports exceeding 20 million, use the Hong Kong company direct procurement model: base the procurement operations in Hong Kong, record contracts and pro forma invoices in the books, and isolate the risk of missing invoices overseas.
⚠️ But there is one bottom line that must be upheld:If you don't have a receipt, you can't claim a tax refund at the exit. However, you can still purchase tax-free items without a receipt, which is in compliance with regulations.If anyone tells you, ”You can get a tax refund even without a ticket,” just ignore them. .
Compliance transition is better sooner rather than later, the earlier the layout, the lower the cost, the more stable the development.
📌 If your business is in one of the following stages:
[Start-up period] Annual revenue < 20 million: Worried about the impact of zero filing, private collection, and Golden Tax Phase IV?
We have the corresponding solutions and practical experience.
👉 Scan the QR code to add our online customer service representative (WeChat ID: jxhqcy890 / Mobile: 16625410105)), arranging professional managers to answer queries and provideFull Process Compliance ProgramOne-to-one service ↓↓↓
Tags:
E-commerce Tax and Financial Compliance in Shenzhen
Shenzhen Tax Compliance
Cross-Border E-Commerce Taxation
buy orders to sell goods (e.g. for export)
Safeway model
Cross-border e-commerce fiscal compliance
Financial and Tax Compliance
Recommended
Foreign funds repatriated this way are taxed at only 1% and are compliant!
How to collect overseas trade funds? Is there a safe and compliant way to operate? There are funds in foreign countries, usually individuals or companies in business transactions with foreign companies and generate revenue, this situation in fact, there are ways to comply with the legal operation, and the return of the tax rate is extremely low! Before we provide the method, let's first understand how most people do it?
Cross-border e-commerce Amazon small team annual income of 20 million, how to do financial and tax compliance?
Amazon four people small team annual income of 5 million, the main body is a general taxpayer but did not do the tax rebate, withdrawals to the boss's private card, that now, want to develop more products, if the collection of more than 20 million, how to comply with the collection to do this fiscal compliance?
Export tax refunds are difficult and complicated?The latest export tax refund filing conditions process in 2024!
For some newly established or just started to have export business of foreign trade enterprises, the whole process of export tax rebate declaration is in a state of ignorance, do not know how to handle, where to go, the process and so on. In this article, we organize the process from the filing of export tax rebate (exemption) to the declaration of export tax rebate, as well as the latest policy in 2024.